
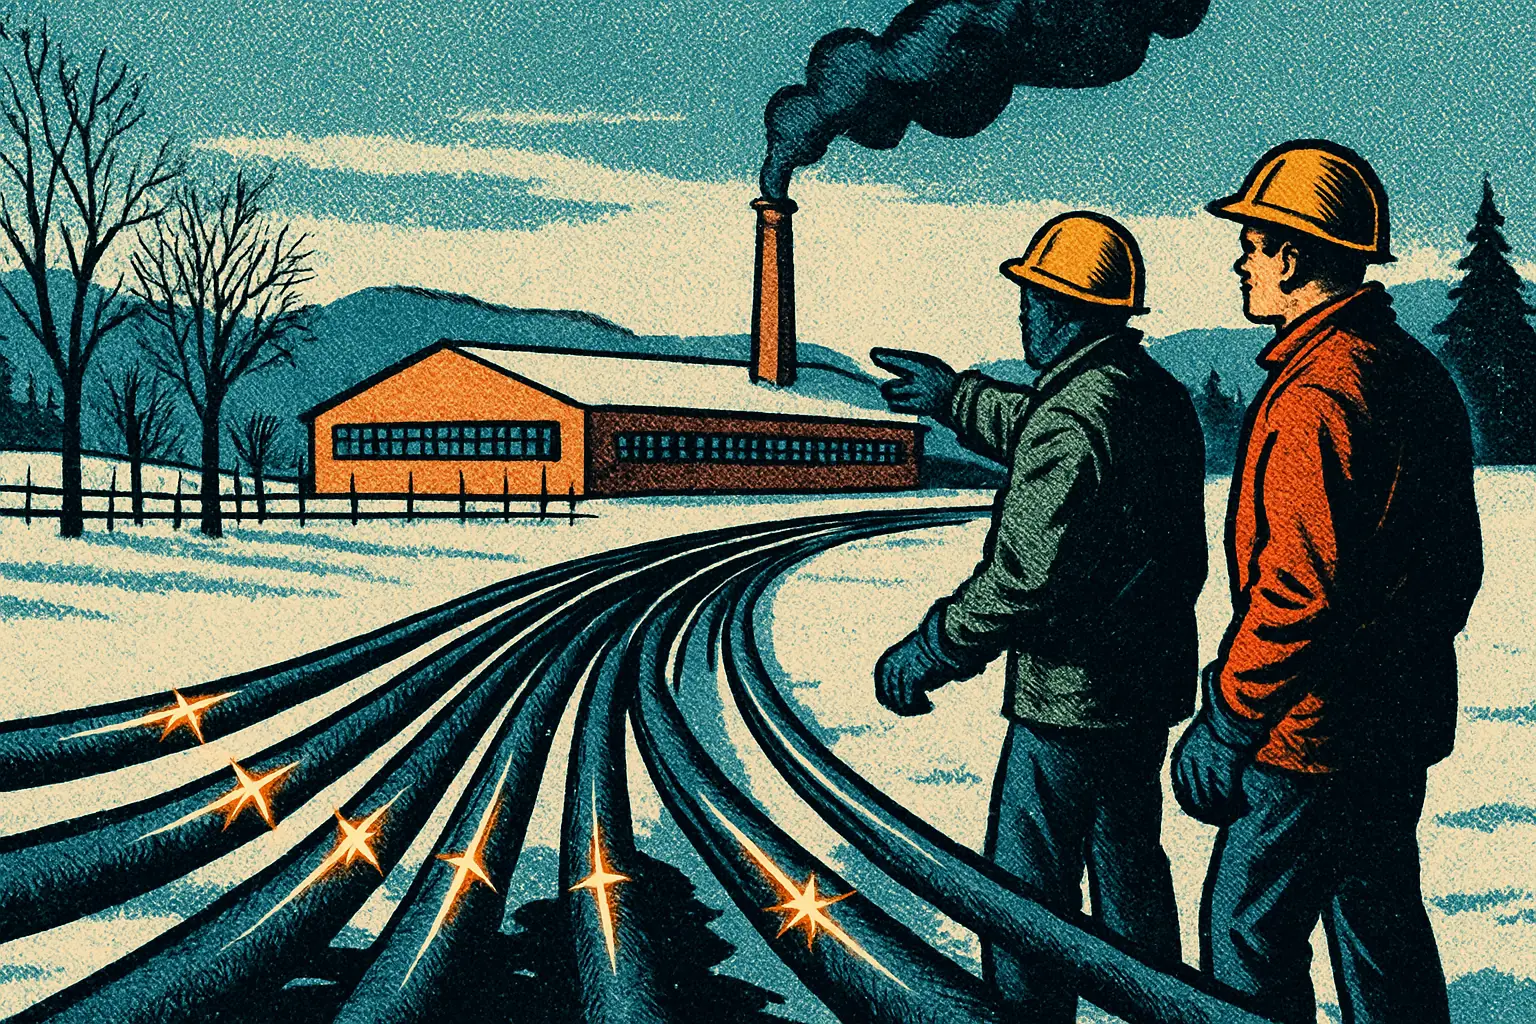
GlobalFoundries and Marvell Expand Vermont SiGe Fab
GlobalFoundries and Marvell expanded a multi-year deal to add silicon germanium capacity in Vermont for 200G-per-lane AI data center optics.
The Bottleneck Moved From Compute to Cable
The story investors keep telling about AI infrastructure is a GPU story. The more interesting constraint right now is the wire between the GPUs. On September 17, 2026, GlobalFoundries and Marvell Technology announced an expanded multi-year agreement to increase silicon germanium capacity at GF's Burlington, Vermont fab, aimed squarely at the optical links that hold AI clusters together.
- What expands: SiGe manufacturing capacity in Burlington, Vermont, described as adding significant capacity for Marvell's requirements
- What it feeds: pluggable optical transceivers, Near-Packaged Optics and Co-packaged Optics
- Current node capability: 200G-per-lane optical connectivity, with a roadmap to higher speeds
- Market reaction: GFS shares closed up 6.53 percent on the announcement day on volume around 6.4 times the daily average, per StockTitan
- Not disclosed: wafer volumes, contract duration in years, and dollar value
What Is Silicon Germanium and Why Does AI Need It?
Optical networking is a hybrid business. The photonics move the light; analog silicon drives and receives it. The drivers and transimpedance amplifiers sitting on either side of the optical link have to operate at extremely high frequency with low noise, and that is a job where silicon germanium beats plain CMOS decisively.
GF's position here is not an AI pivot — it is a legacy asset finding a new market. Shankaran Janardhanan, GF's senior vice president for photonics and RF, framed it as decades of high-performance radio frequency and analog leadership translating into optical performance. The Burlington fab is the former IBM facility, and RF is what it has always been good at.
On the demand side, Marvell's Robb Johnson, VP of foundry technology, made the AI argument directly: connectivity is becoming increasingly critical to unlocking the performance of these systems. A modern training cluster is a distributed computer, and its effective throughput is set by how fast data moves between accelerators as much as by the accelerators themselves.
What Do NPO and CPO Change?
This is the part that makes the capacity commitment interesting rather than routine.
Today most data center optics are pluggable modules — the transceiver sits at the faceplate and copper carries the signal to the switch chip. Near-Packaged Optics moves the optical engine onto the same substrate as the switch ASIC. Co-packaged Optics moves it into the package. Each step shortens the electrical path, which cuts power per bit and lets link speeds rise.
It also changes the supply chain. A pluggable module is a separately manufactured part; a co-packaged one has to be built alongside the silicon. Converge Digest's read is that as links migrate toward NPO and CPO, manufacturers need dedicated analog capacity that scales with photonics, and GF's combination of SiGe, silicon photonics and advanced packaging offers a single pathway for that. Marvell's roadmap spans 200G-per-lane PAM4 DSPs, silicon photonics light engines, coherent DSPs and CPO architectures — all of which need the same analog front end.
What Should Investors Take From It?
Three things, stated carefully.
First, this is a capacity agreement, not a revenue announcement. No wafer numbers, no dollar figure, no stated term. The 6.53 percent move reflects positioning rather than disclosed earnings impact, and StockTitan notes a comparable GFS capacity announcement on September 9 produced a far smaller 1.97 percent move — so the market is pricing something specific about this one rather than capacity news generally.
Second, it is a supply-chain story with a real physical asset behind it. Expanding an existing Vermont fab on a proven process is a lower-risk way to add capacity than greenfield construction, and the two companies have worked together for more than a decade.
Third, optical interconnect is becoming its own investable layer of the AI build-out rather than a footnote to the accelerator trade — the same widening we noted around Marvell's custom silicon deal for Google TPUs and the domestic memory capacity discussions in the SK hynix and Intel Ohio talks. None of that is a recommendation; it is where the capital is visibly going. More in our stock trading coverage.
Sources: GlobeNewswire — GlobalFoundries press release — September 17, 2026; Converge Digest — September 17, 2026; StockTitan — September 17, 2026.
More Stock Trading Stories
Single-Stock Futures Are Coming Back to US Traders
Crypto.com's Nadex completed SEC notice registration on September 14 to list single-stock futures, and is working toward US single-stock perpetuals next.
SK hynix Explores First US Memory Production at Intel
Reuters reports SK hynix is weighing memory manufacturing at Intel's Ohio site. The company confirms it is exploring options but nothing is signed.
Euclyd Lands €200M From Samsung for Inference Chips
Dutch startup Euclyd raised a €200M+ Series A co-led by Samsung to build CRAFTWERK, a non-GPU inference chip with 16,384 in-memory processors.